
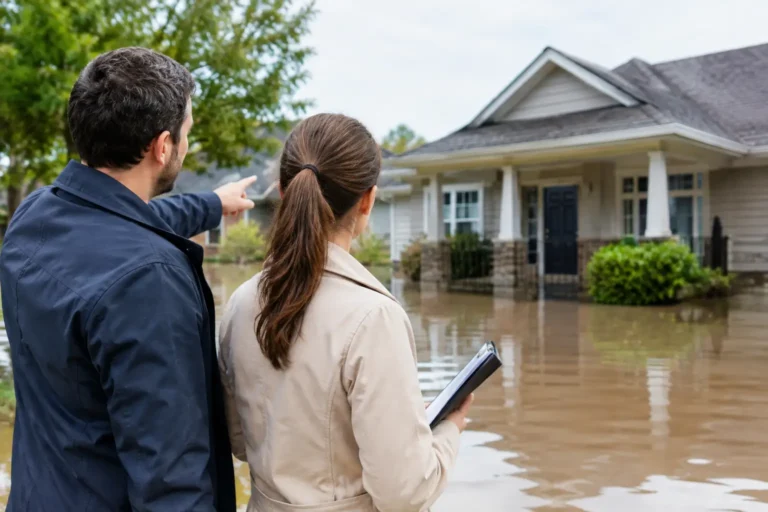
A home can look completely dry on a sunny showing day and still have a history that changes a buyer’s decision. So, do sellers disclose flooding? In most South Carolina and North Carolina residential transactions, sellers must complete state-required disclosure paperwork or address disclosures in a legally recognized way. The practical answer is that known flooding, water intrusion, drainage issues, and related repairs should never be treated as minor details.
For coastal Carolina buyers and sellers, the issue deserves more than a quick checkbox. Flooding can come from a hurricane, heavy rain, a nearby creek, poor grading, stormwater backup, tidal conditions, or a failed drainage system. The source, frequency, severity, repairs, and available documentation all matter.
Do Sellers Disclose Flooding in South Carolina?
South Carolina sellers commonly use the Residential Property Condition Disclosure Statement. This form asks sellers to disclose their actual knowledge of specified property conditions, including water and drainage concerns. Questions address whether the property has experienced flooding, whether water has entered the structure, and whether there are known drainage, erosion, or related issues.
A seller should answer based on what they know, not on what they hope a buyer will discover later. If a crawl space took on water during a major storm, if a garage flooded after prolonged rainfall, or if water has entered the home more than once, the disclosure should provide a clear and accurate response. Vague answers can create confusion precisely when a buyer needs facts.
Not every wet spot means a property has a serious flood history. A one-time plumbing leak is different from stormwater entering the living area. Still, the distinction should be explained rather than left for a buyer to guess. Sellers should describe the event, identify the source if known, and state what repairs or corrective work were completed.
Some transactions may qualify for an exemption from the standard seller disclosure requirement, such as certain estate or court-directed sales. An exemption does not give anyone permission to conceal a known material condition. The details of an exempt transaction should be reviewed carefully with the appropriate professionals.
North Carolina Flood Disclosures Require Careful Answers
North Carolina uses the Residential Property and Owners’ Association Disclosure Statement. Sellers can generally make representations about conditions on the form or indicate that they make no representation for particular items. That choice does not make it wise to stay silent about a known water problem, especially one that could affect a buyer’s safety, use of the home, insurance options, or financing.
North Carolina also follows the long-standing principle that buyers should investigate a property thoroughly. That makes buyer due diligence essential, but it is not a reason for a seller or real estate professional to misstate a known condition. Real estate licensees have duties concerning material facts, and a known flooding issue can be material to a transaction.
For a seller, the safest approach is straightforward: be accurate, be specific, and keep records. For a buyer, the right approach is equally direct: read every disclosure, then independently verify the home’s flood exposure before the inspection period ends.
What Counts as Flooding or a Water Issue?
Flooding is not limited to a named hurricane or a home located in a designated flood hazard area. A house can sit outside a mapped high-risk zone and still experience water intrusion. Conversely, a home in a flood zone may never have flooded during its current owner’s tenure. The flood map is a key tool, but it is not the full story.
Buyers should ask follow-up questions when disclosures mention any of the following: water entering a house, crawl space, garage, storage area, or outbuilding; standing water in the yard; drainage ditches or swales that overflow; ponding near the foundation; erosion; roof runoff directed toward the home; sump pump use; sewer or storm drain backup; or past flood-related insurance claims.
The timing matters, too. Water issues that occur only during exceptional weather may carry a different level of concern than water that appears after ordinary summer thunderstorms. A thoughtful disclosure explains the conditions. For example, “water entered the detached garage during Hurricane Florence and drainage was improved in 2019” is far more useful than simply checking yes without context.
A Seller’s Best Preparation Before Listing
Sellers should not wait until a buyer raises a question to locate flood-related records. Gather documents before the home enters the market, including repair invoices, contractor reports, drainage plans, permits, receipts for mitigation work, photos from before and after repairs, and any available flood insurance documentation.
Then review the disclosure form slowly. A rushed answer is where avoidable problems begin. If you are unsure whether an event qualifies as flooding, describe what happened rather than trying to apply a label. State where water appeared, when it occurred, what caused it if known, and what was done afterward.
Do not make promises a property cannot support. Saying a home “will never flood” is rarely defensible, particularly near the coast, along waterways, or in areas with changing drainage patterns. A seller can share improvements and history without guaranteeing future conditions.
It also helps to make improvements visible and understandable. If the home has a repaired crawl-space moisture issue, a new drainage system, elevation work, or redirected downspouts, have the related records organized for review. Buyers tend to respond better to a well-documented issue that was responsibly addressed than to a surprising discovery late in the transaction.
How Buyers Should Verify a Flood History
A disclosure is an essential starting point, not the finish line. Buyers should review flood maps, request a comprehensive home inspection, and consider specialized inspections when the property or disclosure raises questions. Depending on the situation, that could include a drainage evaluation, crawl-space assessment, roof inspection, or review by a qualified contractor.
Ask the seller for the property’s flood insurance history if it is available, along with details of any prior claims and completed repairs. Buyers should also ask their insurance provider about coverage availability and likely requirements early in the process. If a lender determines flood insurance is required, that can affect the monthly housing payment and should be understood before final loan approval.
Local context matters. In Horry County, Georgetown County, Brunswick County, and other coastal Carolina markets, buyers should look beyond the house itself. Observe the neighborhood’s drainage, nearby ditches and retention ponds, road elevation, waterway access, and signs of recurring standing water. A visit after rainfall can reveal conditions a dry-day tour cannot.
A buyer should never assume that a newly renovated interior eliminates a water concern. Fresh flooring and paint may be perfectly legitimate improvements, but they do not answer questions about prior moisture, drainage, or structural effects. Ask clear questions and request support for the answers.
When a Past Flood Does Not End the Deal
A known flood event is not automatically a reason to walk away. Many homes have experienced storm-related water events and have since received effective repairs or mitigation. The decision depends on the nature of the event, the work completed, the home’s current condition, insurance considerations, and the buyer’s comfort with the remaining risk.
For example, a documented one-time garage event during an extraordinary storm may be manageable for one buyer. Repeated water entry into the living area after routine rainfall is a different situation and deserves more extensive investigation. There is no universal answer, which is why documentation and professional guidance matter.
The Chrzanowski Team at Realty One Group helps buyers and sellers approach property-condition questions with clear next steps, responsive communication, and local market knowledge across the Carolinas. When flooding or drainage is part of the conversation, the goal is not to create fear. It is to make sure the facts are on the table early enough for confident decisions.
If you are preparing to sell, disclose what you know and organize the proof behind your answers. If you are buying, ask the extra question, inspect carefully, and give yourself time to evaluate the response. A well-handled flooding discussion protects the transaction and gives everyone a clearer path forward.
